Editorial President Lee Jae-myung: Will He Go Toward Moon Jae-in Season 2 or Return to Pragmatism?
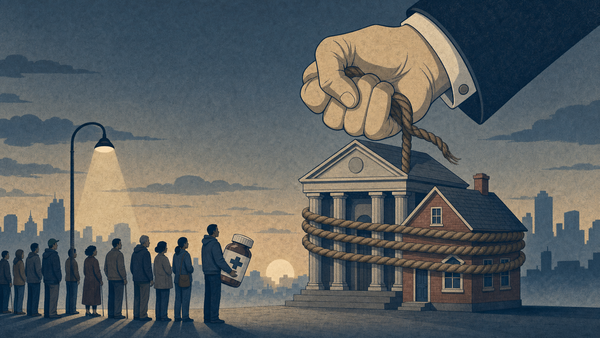
The two pillars of the government's real estate policy are both derailing. One is the tax reform plan. There is a move to adjust the basic deduction for comprehensive real estate tax on non-resident single-homeowners and to reorganize the long-term ownership special deduction based on residence period. The other is quantitative regulation of household loans. This involves setting an upper limit on annual loan growth for each financial company and tightening bank lending windows.
The Limits of Loan Regulation Relying on Administrative Guidance
Let's first examine quantitative regulation. This regulation takes the form of administrative guidance based on financial authorities' macroprudential supervisory authority, but it has been criticized for amplifying market uncertainty because concrete guidelines are not specified in law. Financial companies submit annual targets aligned with the authorities' 'management direction,' and if they exceed them, they face disadvantages in inspections and supervision the following year. The Constitution stipulates that restrictions on people's basic rights are only possible through legislation (Article 37, Paragraph 2) and declares respect for individuals' and enterprises' economic freedom and creativity (Article 119). This is why criticism has emerged in state affairs audits and elsewhere that "uncertainty is so great it borders on abuse of authority," as regulations directly affecting citizens' property rights exercise through window guidance rather than clear legal standards.
When managing household debt, major developed countries mainly secure predictability using legalized standards like DSR and LTV that examine borrowers' repayment capacity. In contrast, the approach of uniformly controlling the total lending volume by financial company tends to cause supply-demand distortions. Like Japan's quantitative lending regulation introduced during the bubble collapse in 1990, excessive artificial restraint measures can deliver unexpected shocks to the market, requiring careful approaches.
Each time authorities have strengthened total volume management by setting loan growth rate targets, market side effects have repeated. Real estate finance has become patched, as authorities repeatedly strengthen regulations, then face loan cliff issues for actual homebuyers, establish exceptions, and relax again. This is why actual homebuyers continue appealing—some receive loan applications from early dawn or anxiously scramble to find down payments for apartments they have purchased. As this cycle repeats—tightening, exceptions when side effects emerge, then relaxing—even the Bank of Korea's Monetary Policy Committee has expressed concern that quantitative regulation erodes the effects of base rate adjustments.
Tracing this drastic treatment's lineage is even more depressing. Setting specific growth rate targets and implementing comprehensive quantitative management in earnest was the Moon Jae-in government in 2021. The year's growth rate targeted at 5-6 percent exceeded the target at 7.1 percent, and after banks stopped new lending at year-end, creating a loan cliff for actual homebuyers, they hastily exempted jeonse loans.
The Lee Jae-myung government revived that failed remedy and applied it more harshly. Starting with the June 27 plan last year that capped mortgage loan limits at 600 million won across the board, through the September 7 and October 15 plans, it differentiated limits to 600 million, 400 million, and 200 million won depending on house prices, and in April this year, under the banner of 'severing ties between real estate and finance,' tightened household loan growth to 1.5 percent. Then within four months, it raised the white flag. 'Loan open runs' became routine, with registration closing in ten minutes after 6 a.m. reception, and appeals from actual homebuyers unable to find down payments on purchased apartments erupted at a presidential discussion forum, prompting the government to announce on the 13th a measure doubling the total volume target to 3 percent. With the cycle of tightening, adding exceptions when side effects emerge, and relaxing, real estate finance has become patched. Even the Bank of Korea's Monetary Policy Committee expressed concern that quantitative regulation erodes the effects of base rate cuts. Is the government holding onto policies that cannot even project four months ahead while asking citizens to make life plans?
Damages to Actual Homebuyers Caused by Inelegant Tax Design
The tax system also lacks sophisticated design. Despite the government's intent to strengthen taxation on non-resident single-homeowners from a tax justice perspective, the current tax system risks imposing excessive burdens on well-intentioned actual homebuyers. Prime examples include office workers who temporarily vacate homes due to transfers or work circumstances and those who became non-resident single-homeowners due to inherited shares.
Of course, tax law provisions for exceptional circumstances such as work-related reasons or medical necessity exist, but the verification procedures are cumbersome and requirements are strict, creating blind spots. Additionally, problems arise when single-homeowners temporarily unable to meet residence requirements during the home transfer process face excessive transfer tax burdens. Transfer gains arising from residential relocation are not income accumulating in bank accounts but residential relocation funds to move into the next home. In a situation of overall housing price appreciation, excessive transfer tax assessment can constrain upward residential mobility.
Major countries like the United States and Britain grant generous deduction limits for owner-occupied homes or operate flexible reduction systems proportional to residence period to guarantee residential relocation for single-homeowners. Taxation on actual-use single-homeowners must be finely calibrated to prevent market speculation. Improving mechanical designs that penalize based solely on possession and residence period and establishing straightforward remedies that open pathways for actual homebuyers to upgrade their housing are necessary.
Must Return to Market Communication and Predictable Policy
We have seen this scene before. The Moon Jae-in government, under the banner of 'war on speculation,' unleashed over twenty measures over five years. Heightened transfer taxes on multi-homeowners increased gifts instead of property listings, and demand avoiding tax burdens concentrated on 'one solid property,' pushing up Gangnam housing prices. The Rental Housing Act amendments (Jeonse 2 Law) came back as the disappearance of jeonse listings and soaring jeonse prices. After confirming for five years how policies designed with good intentions and logic face retaliation in the market, the current government now walks the same path, reviving quantitative regulation and further tightening the tax system. It is strange that 'Moon Jae-in Season 2' is not being mentioned.
No matter how good the intentions, policies ignoring market principles produce unintended side effects. We must not repeat the past experience where multi-homeowner regulations created property shortages and 'one solid property' concentration. We have already confirmed multiple times what confusion policy designed with mere good intentions and enthusiasm brings to markets.
Enforcing foreseeable side effects is not conviction but stubbornness. The government must boldly change what should be changed by accepting voices from the field. It must stop short-term remedies starting from presidential ideas and return to verified, predictable, stable policy from advanced nations. Publishing a roadmap to convert quantitative regulation into borrower-unit regulation based in law and boldly reducing tax burdens on single-homeowner actual users is the starting point. Under a policy structure of chronic extreme medicine doses, normal market operation cannot be expected.
Whether tomorrow's (18th) press conference will be the curtain-raiser for Moon Jae-in Season 2 or the beginning of pragmatic President Lee Jae-myung's government depends on President Lee Jae-myung.